The lease that produces information, and the lease that produces expensive housing
By Ariel Lima ·
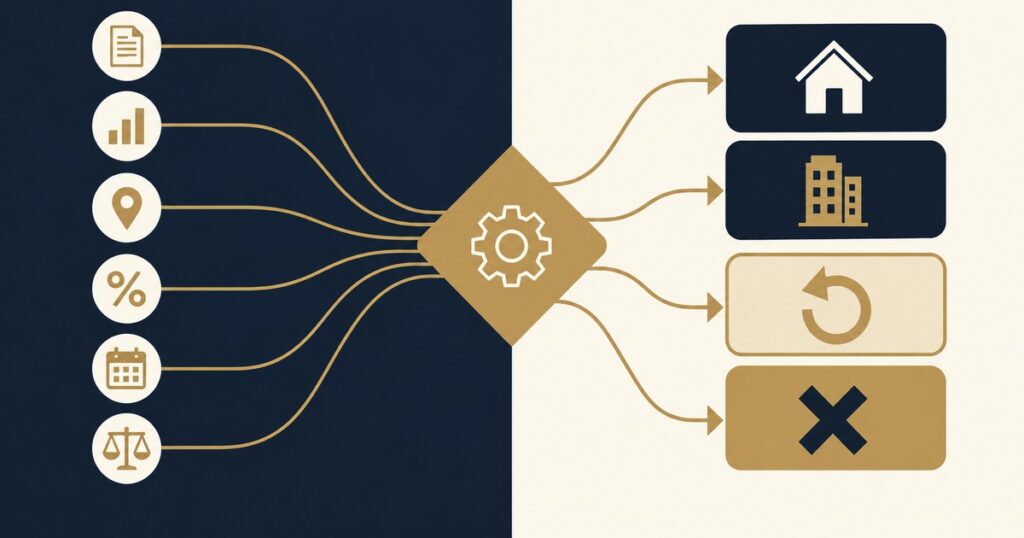
Six variables, four exits: the decision procedure for renting before buying
Two earlier analyses from this practice established two different things. The first, that the public record does not contain what decides between two buildings of the same tier: how a building operates in August against how it operates in January, whether the amenity program is used or ornamental, how management behaves when something fails. The second, that there is at least one case where the comparable sits a hundred metres from the target asset.
Neither one says how to choose.
This piece is the procedure. It is not a recommendation to lease: of the four exits it admits, two produce no purchase at all. It is the procedure for determining whether renting before buying applies, and if it does, which contract produces usable evidence.
The interest declared
This practice operates in the Bal Harbour – Sunny Isles corridor and would earn a commission on a lease in the corridor, on the purchase that may eventually follow it, and on a sale in One Bal Harbour, whose closed records supply the figures below. The reader should weigh that against everything that follows.
First: whether the year applies at all
The first question is not where. It is whether.
Before the six variables there is a single disqualifying condition: what material uncertainty is the residence meant to resolve, and what allocation decision would change based on what is observed?
If the reader knows the submarket and the tier thoroughly — because they have lived there recurrently for years, because they already operate a comparable asset, because the decision is made and only execution remains — additional evidence has marginal value. The correct output of the procedure is not to lease, and to proceed with allocation analysis on the specific asset.
The information year is not a mandatory step. It is an expense justified when a relevant uncertainty exists that lived evidence can actually reduce. Where that uncertainty does not exist, it is a cost with no return.
What this condition settles and what it does not. It establishes whether renting before buying applies. It does not establish where, for how long, or under what structure.
The six variables, and what each one tests
A comparable lease is not a similar lease. Renting before buying produces evidence only when the lease puts the variables informing the purchase under test. Six of them, each answering a different question:
Location and living pattern. Tests whether the submarket is compatible with the intended use: real distances, seasonal traffic, guest access, how an ordinary day resolves. It fails when the lease is taken in an adjacent submarket assumed to be equivalent. Cost of the failure: twelve months observing a living pattern that is not the one being bought.
Density. Tests the experience of actual occupancy: how many people are in the elevators, at the pool, on the beach, in the garage, and in which months. It fails when the leased building has a materially different residence count from the target. A building of 56 residences — 61 as designed, fewer once buyers combined adjacent units — and a building of 240 do not produce the same daily experience, even sharing a tier and a block.
Resident profile. Tests who actually lives there: proportion of primary residence, presence of families, turnover, seasonal use. It fails when the leased building has a very different ownership composition. It is the least visible variable from outside and the one that most determines the building’s daily character.
Service standard. Tests what the building actually delivers rather than what it advertises: response time, staff turnover, behaviour under load in high season. It fails when the leased building operates at a different service tier. It is the variable sales material describes with the most enthusiasm and the least evidence.
Operating model. Tests how the operation is organised: whether there is a hotel operator, whether transient-occupancy units sit inside the same structure, whether management is in-house or contracted. It fails when the leased building’s model differs structurally from the target. A building with hotel inventory deeded onto the same floor plate as the residences is not a proxy for a purely residential building.
Governance structure, where comparable evidence exists. Tests how decisions are made and how they are funded: operating budget, reserve level, assessment history, the relationship between residents and management. The qualification matters: where the target is pre-construction, there is no governance to compare, and this variable is inferred only with caution.
The rule governing the set: a lease selected on rent or price alone does not produce diligence; it produces expensive housing.
What these six settle and what they do not. They name what has to match. They do not rank themselves by weight, and the relative weighting shifts with the mandate.
The exclusion, and why it exists
The procedure excludes contracts shorter than twelve months. The reason is not duration. It is seasonality, and the corridor’s own data shows it directly.
At One Bal Harbour, 10295 Collins Avenue, six contracts closed across twelve running months: three on six-month terms and three on annual or longer terms. What orders those six figures is not the term. It is the month of closing.
The two most expensive six-month contracts per foot closed in December and January — $12.67 and $11.70 per square foot per month — inside high season. The third six-month contract closed in September at $7.02: below the other two by a wide margin, and inside the range of the annual contracts.
| Term | Mean | Range | n |
|---|---|---|---|
| Six months | $10.46/SF/mo | $7.02 – $12.67 | 3 |
| Annual or longer | $7.32/SF/mo | $5.35 – $8.65 | 3 |
The difference in means is 42.9%. It is stated as arithmetic on three records against three in a single building, not as a market result: a sample that size establishes a direction, not a distribution. What supports the exclusion is the month of closing, not the average.
Renting before buying on a term that spans a single season measures that season’s price, not the building’s behaviour. And for diligence purposes, a term that does not cross the full cycle does not permit observation of the variation that is precisely the object of the observation.
For the same reason, twenty-four-month contracts are not excluded: they cross the cycle exactly as an annual one does. The exclusion is not against long duration; it is against a term that does not cover the year.
What this exclusion settles and what it does not. It establishes which contracts produce comparable evidence. It does not establish which term fits a particular calendar.
The four exits, with their conditions
A procedure without defined exits is not a procedure. Each one has its condition.
Buy during the lease. Condition: the evidence completes before expiry and the target qualifies. The framework does not fix when that happens; some of the six variables resolve in the first months and others require the full cycle, and which ones dominate depends on the mandate. A warning worth naming: buying does not extinguish the lease. Rent runs to expiry. Where the purchase is structured one or two months before the term ends — to allow time to furnish and prepare the move — those months are paid twice, rent and ownership carry simultaneously.
Buy at the end of the term. Condition: the observation set is complete, the target qualifies and the opportunity is still available. It is the exit the framework assumes by default and it is not the most frequent.
Lease again. Condition: the question remains open, or the specific target is not available in the window. It is not a failure of the procedure. It is the correct result when the evidence does not yet resolve the decision, and the marginal cost of a second year is weighed against the same allocation the first year informed.
Do not buy. Condition: nothing observed qualifies. The submarket does not match the intended use, the tier does not support the price, or the lived evidence contradicts what the documentary material suggested.
That last exit deserves a line, because it is what distinguishes a procedure from a recommendation. A framework whose valid output includes do not buy is difficult to publish for an operator whose compensation depends on the purchase happening. Two of these four exits produce no purchase transaction at all, and both are inside the procedure by design rather than as a concession.
The fifth configuration
There is a fifth that is not an exit but an overlay, and it is the highest-value one when the target is pre-construction.
In pre-construction the building does not exist. There is no management to evaluate, no service standard actually delivered, no resident profile to verify. The buyer signs, deposits, and waits three to five years to discover whether they paid for an operating standard or a logo.
In that configuration renting before buying stops being a cost incurred before the purchase. The buyer executes the pre-construction contract, leases a comparable of the same tier during construction, and arrives at delivery having verified in a real building the variables their own cannot yet show. The cost of the lease stops being the price of waiting and becomes the price of living somewhere while the wait happens.
A limit worth naming: a good comparable reduces operating uncertainty, but it does no diligence on construction execution, delivery quality, or the future economics of an association that does not yet exist. That is documentary and specialist work, handled separately.
What the procedure does not resolve
The six variables can be verified. The four exits can be anticipated. There is one variable that admits neither.
Delivery dates move.
A lease term set against a projected delivery is a position on a developer’s schedule. If delivery comes early, the lease overlaps and is paid twice. If it slips eighteen months with four months left on the contract, the buyer has capital committed to an asset that does not exist and nowhere to wait for it.
That risk is not eliminated by adding a variable to the list. It is managed through the structure of the contract, and the right structure depends on things no published list contains.
With a target in view and a window to work in, the six variables and the four exits above are enough to run the decision on renting before buying. What they do not cover is the term itself when the target’s delivery can move — how much slack to build in, when a renewal option beats a longer initial term, and what to do when delivery slips eighteen months with four left on the contract. Those depend on the specific developer’s delivery record and on the specific contract’s delay provisions. With those two in view, the term is structured against a real calendar instead of a projected one. Send the project and the window.
Lease figures come from closed transaction records in the South Florida MLS for One Bal Harbour, 10295 Collins Avenue, across the twelve running months verified as of August 2026: six contracts, three on six-month terms and three on annual or longer terms. Area: Adjusted Square Footage from the Miami-Dade Property Appraiser. This document is educational. It does not constitute an offer to sell or investment, tax or legal advice.
The monthly corridor analysis. One a month.